Net debt is the debt included in a calculation minus the cash eligible to offset it. A simple measure starts with funded borrowings such as outstanding bonds, bank loans and drawn credit lines. Debt-like items are other obligations, such as some lease liabilities or a pension funding shortfall, treated as debt for a specific calculation. The choice matters when moving from enterprise value to equity value. Each extra claim outside the operating valuation reduces the amount left for shareholders.
The same balance sheet can give two answers
A fictional company has funded debt of 100 million USD and 30 million USD of eligible excess cash. Here, eligible cash is available to the company on the valuation date after it sets aside what it needs for day-to-day operations. The company cannot use blocked balances to pay these claims. If the operating valuation already includes cash needed for operations, adding that cash in the bridge would count it twice. Damodaran, Working Capital in Valuation
The simple measure gives million USD. The company also has a 20 million USD pension deficit, measured as the present value of promised benefits less the fair value of plan assets, and a 15 million USD lease liability. Suppose the lease financing payments and catch-up contributions for the existing pension deficit are outside the operating valuation. Both liabilities are separate from funded debt and every other line in the bridge. The adjusted deduction is million USD. IFRS Foundation, IAS 19, defined benefit plans
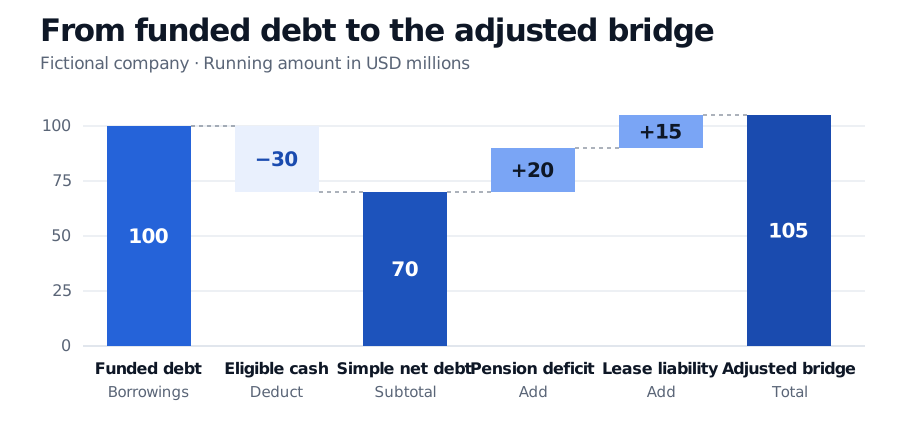
The two added obligations increase the amount deducted from operating enterprise value by 35 million USD.
If forecast free cash flow already includes the payments that settle a liability, leave that liability out of the separate deduction. When treating an existing lease as financing, keep future asset replacement in the operating forecast. The same matching principle applies to EV/EBITDA. If EV includes the lease liability, use EBITDA before the corresponding lease charge. Add back the charge only if it actually reduced the starting EBITDA. Damodaran, Dealing with Operating Leases in Valuation
A non-controlling interest belongs on a separate equity line. If the operating valuation includes an entire subsidiary, deduct the value of the outside shareholders’ stake to reach the parent’s common equity value. Damodaran, Getting to Equity Value per Share
Which definition governs?
- Reported metric. Read the issuer’s reconciliation. American Airlines’ full-year 2025 release included finance leases, operating leases and pension obligations in its reported non-GAAP measure, then deducted unrestricted cash and short-term investments. Adding those same lease or pension amounts again would overstate debt. American Airlines, Total Debt and Net Debt
- Financial covenant. Use the agreement’s definitions of debt, eligible cash and EBITDA, including which subsidiaries count. DaVita’s November 2025 amendment removed a cash-netting cap from its leverage ratio definition. The applicable version of the agreement can change the result even when the balance sheet stays the same. DaVita, Eighth Amendment, Annex A
- Closing price. Apply the purchase agreement’s definitions and measurement time. The November 2025 Topgolf agreement excluded operating leases from closing indebtedness and defined cash to include restricted cash. It also excluded amounts already captured as debt or unpaid transaction expenses from the working capital calculation. Putting the same obligation in two adjustments would reduce the price twice. Topgolf Callaway Brands, Equity Purchase Agreement, §§1.01 and 2.05