Lesson 1 · Intermediate · 18 min
The Binomial Model
✓Before this: Market Model and Risk-Neutral Valuation
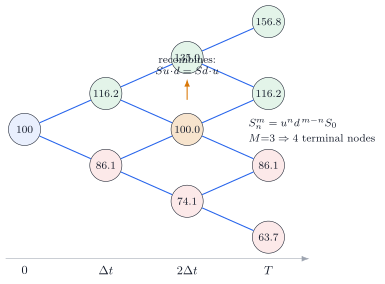
One-step binomial model and replication
Over one period the stock moves or with . Replicating the option with shares and cash forces
Here are the option’s known values in the two successor states, and is the risk-neutral probability: it is a genuine probability exactly when , which is forced by no-arbitrage. Real-world probabilities never enter.
Financial interpretation. The hedge ratio Δ is the discrete ancestor of . Pricing by replication and by discounted risk-neutral expectation give the same number because the price is the cost of the hedge.