Guaranteed minimum benefits are contractual floors on specified benefits in a variable annuity, whose account value depends on investment performance. When the contract calls for a benefit and the investments cannot support the promised minimum, the insurer covers the shortfall. That creates an option-like liability that can grow when markets fall. Reinsurance Group of America, 2024 Annual Report
What does the contract guarantee?
The account value is the current value of the investments held under the contract, after any deductions already made. A benefit base is a separate contractual amount used to calculate a guarantee. It can stay above the account value after a market fall. Some riders step up the base after gains on specified dates or reduce it after withdrawals. The base itself serves as a calculation input. Cash available on surrender follows the contract's separate surrender terms. Brighthouse Variable Annuity Contract prospectus
| Guarantee | What it protects |
|---|---|
| Guaranteed minimum accumulation benefit (GMAB) | A minimum account value on a specified date if the contract remains eligible. |
| Guaranteed minimum death benefit (GMDB) | A minimum payment to the beneficiary on a qualifying death. |
| Guaranteed minimum withdrawal benefit (GMWB) | A schedule of permitted withdrawals that can continue after the account reaches zero, subject to the rider's limits. A lifetime version can continue while the covered person lives. |
| Guaranteed minimum income benefit (GMIB) | A minimum income stream when the owner elects eligible annuitisation. The rider's conversion terms turn the income base into a periodic payment. |
The payout trigger tells the modeller what to project. For a GMAB, the modeller compares the account balance with the guaranteed amount on the specified date. Earlier account values can matter when the contract uses them to step up that amount. A GMWB can require a full path of withdrawals and account balances to determine when the insurer starts funding the payments. Brighthouse Variable Annuity Contract prospectus
A 15-unit shortfall
Take a simplified accumulation guarantee with a single cash settlement at date . The floor is fixed at 100 currency units. Assume the contract stays in force and ignore fees, surrender, withdrawals and ratchets. With account value immediately before settlement, the insurer pays
At an account value of 85, the insurer adds 15, bringing the total to 100. At an account value of 125, the top-up is zero and the owner keeps 125. The top-up has the terminal payoff of a European put option on the account value, with the floor as its strike. Withdrawal, death and income guarantees each need their own trigger and cash-flow rules.
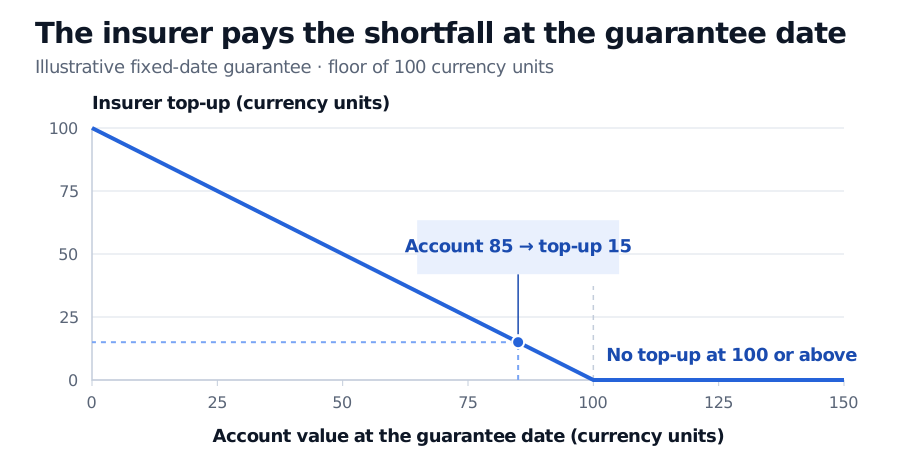
Below the floor, each unit the account loses adds one unit to the insurer’s payment. At the floor and above, the insurer owes zero under this illustrative guarantee.
What the hedge offsets
An insurer measures how the value of its guarantee liabilities responds to equity prices (delta), interest rates (rho) and implied volatility (vega). A hedge portfolio can use equity futures and options and interest-rate swaps to offset changes in that value. As markets and contract exposures change, the insurer re-estimates sensitivities and adjusts the hedge. Ameriprise Financial, 2025 Form 10-K, Item 7A
Residual risks include basis risk if the actual funds diverge from the indices used to hedge them. Policyholder behaviour also changes claims. A surrender can end the guarantee, and the timing and size of withdrawals change when the account runs out. Lifetime benefits bring longevity risk because longer survival can mean more payments. Equity and rate derivatives address market sensitivities and leave these behavioural and demographic exposures with the insurer. Manulife, Variable Annuity Dynamic Hedging Strategy
The Stochastic Modelling for Retirement Products lesson shows how to simulate guarantee cash flows and estimate hedge sensitivities. The preview is public and the full lesson requires membership.