A million-dollar base, a smaller payment
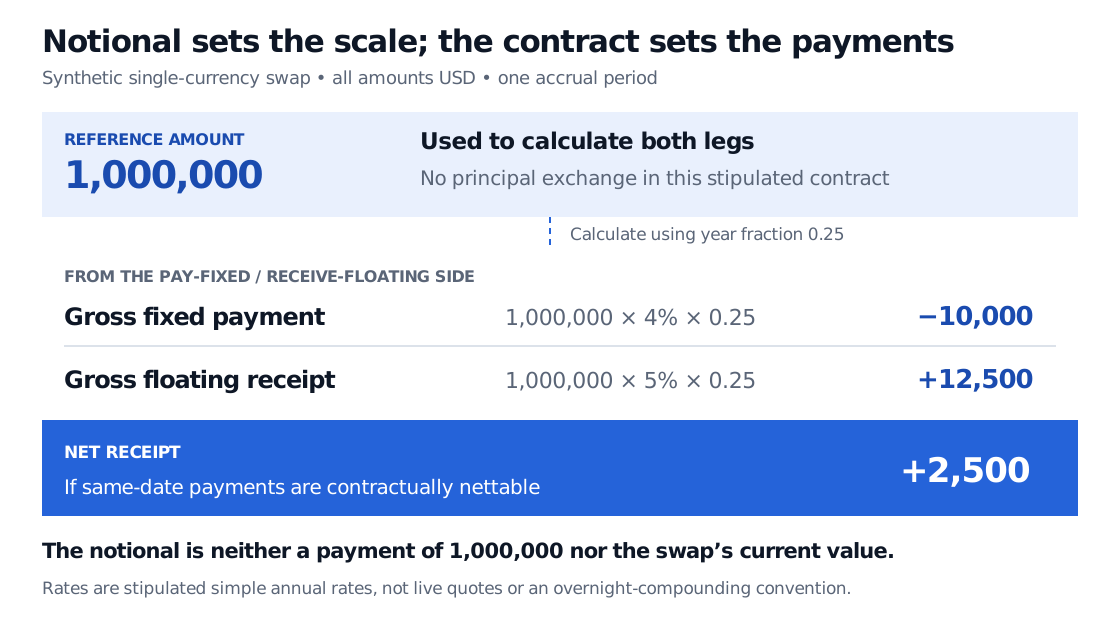
Consider a synthetic single-currency swap with USD 1,000,000 notional. For one accrual period, stipulate a simple fixed rate of 4% per year, a simple floating reset of 5% per year and the same year fraction of 0.25 for both legs. Both payments fall on the same date. These are illustrative contract assumptions, rather than a claim about a particular benchmark's conventions.
For each leg, the calculation is
where is notional, is that leg's annual rate and is its contractual year fraction. Actual day-count conventions determine the accrual fraction; “one quarter” need not universally mean 0.25.
From the perspective of the party paying fixed and receiving floating:
| Cash flow | Calculation | Signed amount |
|---|---|---|
| Fixed leg paid | USD 1,000,000 × 0.04 × 0.25 | −USD 10,000 |
| Floating leg received | USD 1,000,000 × 0.05 × 0.25 | +USD 12,500 |
| Net receipt, if contractually nettable | USD 12,500 − USD 10,000 | +USD 2,500 |
The other party has the opposite signs and pays USD 2,500 net. Without contractual payment netting, retain the two gross obligations. In this stipulated plain-vanilla example, neither party transfers the USD 1,000,000 principal.
What the notional does not measure
Other amounts answer different questions:
| Amount | What it tells you |
|---|---|
| Notional | The contract's reference scale |
| Option premium | The price paid for an option |
| Margin or collateral | Resources posted to support contractual obligations |
| Maximum loss | A property of the payoff, position and contractual terms; it cannot generally be read from notional alone |
Read the principal terms
When reading a trade confirmation, identify the currency and notional schedule, the rate or payoff applied to it, the accrual and payment conventions, and any principal exchanges. Those terms turn the reference amount into actual obligations.
Sources
- John C. Hull, Options, Futures, and Other Derivatives, 9th Global Edition, Pearson, 2018, §7.1, pp. 175–176, and §7.13, p. 201: notional principal, gross interest payments, net settlement and scheduled changes in principal.
- Reserve Bank of Australia — Interest Rate Swaps, RDP 9409, §2: reference principal and single-currency swap mechanics. Historical examples illustrate mechanics rather than current benchmark conventions.
- BIS — International finance through the lens of BIS statistics: derivatives markets, December 2025: notional versus market value and differences across derivative types.
- HMRC — Corporate Finance Manual CFM13420: principal exchanges in currency swaps, used here for instrument mechanics rather than tax guidance.