Committed capital is the amount an investor contractually agrees to contribute to a private fund. A capital call is a request under the fund agreement to pay a specified amount by a specified date. In a closed-end private equity fund, the investor, or limited partner (LP), makes the commitment. The general partner (GP) typically calls it in instalments to fund investments, fees or expenses. From the moment the LP commits, the fund can create future demands on the LP’s cash within the terms of the agreement. ILPA Model Limited Partnership Agreement
A notice creates a payment to plan for
The notice date is when the GP issues the call, the due date is when the money is owed, and the payment date is when the LP actually transfers it. A call that has been issued but has yet to settle belongs in the LP’s upcoming payments. Paid-in capital records contributions already made. The limited partnership agreement (LPA) specifies what the GP can call, for what purpose and with what notice. For example, the Institutional Limited Partners Association’s (ILPA) July 2020 whole-of-fund model, a template for a Delaware private equity buyout fund, calls for at least ten business days’ notice. Its model also permits certain calls after the commitment period ends, including for fund expenses and qualifying follow-on investments. ILPA model, §§ 6.1–6.2 and 7.4
One distribution, two balances
Suppose an LP commits 100 USD. The GP has called 30 USD against that commitment, and the LP has paid it all. The LP later receives a 10 USD cash distribution that the GP cannot recall. There is no recycling or other commitment adjustment, and no unpaid call. From the LP’s perspective,
The LP has paid 30 USD in contributions and received 10 USD back, while 70 USD remains available to call under the contract. Paid-in capital can include fees and expenses, so the LP needs the breakdown to identify how much funded investments at cost. To value the interest today, the LP needs its share of net asset value (NAV), which reflects current valuations and liabilities. ILPA Capital Call & Distribution Template Guidance, §§ VII–VIII
If the agreement instead lets the GP call back all 10 USD for a permitted purpose, the same cash receipt restores 10 USD of unfunded commitment. The LP still has a cumulative cash outflow of 20 USD, but now has 80 USD that the GP can call under the agreement. This is one way to recycle proceeds for further investment. The fund may also be able to retain eligible proceeds and put them to work without first paying cash out to the LP. The ILPA model illustrates both mechanisms. The distribution waterfall governs who gets the proceeds and in what order. The recycling provisions specify what can be reused. ILPA model, §§ 6.4–6.5 and 14.3
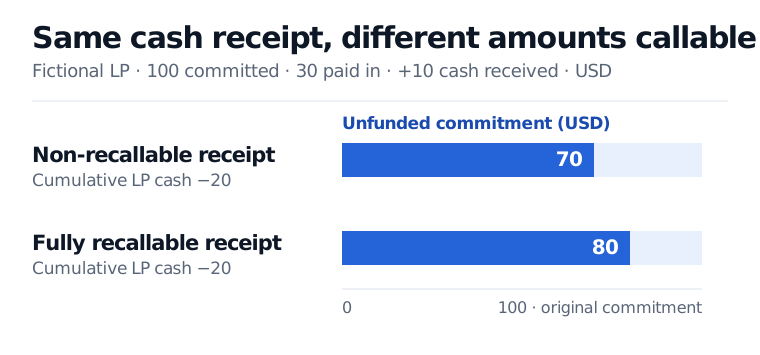
In the fictional comparison, both distributions put the same cash in the LP’s account. Only the fully recallable distribution restores 10 USD of call capacity.
Plan around when the cash is due
An LP reconciles the notice to the cash that settled and tracks how much each transaction changes the remaining commitment. For example, some agreements permit fees to be called outside the commitment. Paying such a fee uses cash and leaves the unfunded balance unchanged. ILPA Capital Call & Distribution Template Guidance, §§ IV and VII
A subscription credit line can fund an investment before the LP contributes. A later call can repay the borrowing, concentrating cash demands even though the investments occurred earlier. For commitment pacing, an LP models calls and distributions across funds to decide when and how much to commit to new funds. A liquidity stress test can move distributions later and cluster payments to see whether available cash and liquid assets still cover the calls. ILPA subscription-line disclosure guidance, “Cash Flow Management Difficulty”
Sources
- Definitions of Commitment and Remaining Commitment, contributions and reuse of proceeds in Article 6, post-period draws in § 7.4 and the waterfall in § 14.3. ILPA Model Limited Partnership Agreement (Whole-of-Fund Waterfall), July 2020
- Reporting guidance on unfunded balances, transaction descriptions and recallable distributions. ILPA Capital Call & Distribution Template Guidance, September 2025
- Discussion of call timing, liquidity and exposure. ILPA Enhancing Transparency Around Subscription Lines of Credit, June 2020