Rule 144A is a U.S. Securities Act safe harbour for certain resales to qualified institutional buyers (QIBs), including sales to purchasers the seller and anyone acting on its behalf reasonably believe are QIBs. Regulation S (Reg S) treats qualifying offshore offers and sales as outside the scope of the Act’s Section 5 registration requirements. Bond registration here means registering the bonds under the U.S. Securities Act so they can be sold under an effective registration statement. For a credit analyst, two lines of the same corporate bond can promise the same payments yet reach different buyers. That can affect which quotes and trades are useful when valuing a position or estimating the cost of selling it. Rule 144A · Regulation S, Rule 901 · Securities Act § 5
One financing, two distribution channels
Suppose a fictional U.S. manufacturer that files SEC reports issues one series of non-convertible notes with identical payment terms across two tranches. It sells both tranches to a dealer acting as initial purchaser. Assume that the issuer’s primary-market sale qualifies for the private offering exemption in Section 4(a)(2). The dealer then distributes the notes in two ways. Securities Act § 4(a)(2)
- U.S. institutional tranche. The dealer resells under Rule 144A. It limits sales to QIBs or purchasers reasonably believed to be QIBs, takes reasonable steps to make buyers aware of its reliance on the rule and satisfies the other applicable conditions. The notes acquired in these resales are restricted securities. Rule 144A, preliminary notes 6–7 and paragraph (d)
- Offshore tranche. The dealer, acting as distributor, offers and sells to non-U.S. persons who are outside the United States and place their orders from abroad for their own accounts. Assume no directed selling efforts in the United States for this tranche and that the distributor meets the Category 2 conditions under Rule 903, including implementing the required offering restrictions. The offshore transaction test looks at the circumstances of the offer and sale. A foreign mailing address alone says little about where an order originates. Rule 902(c), (h) and (k) · Rule 903
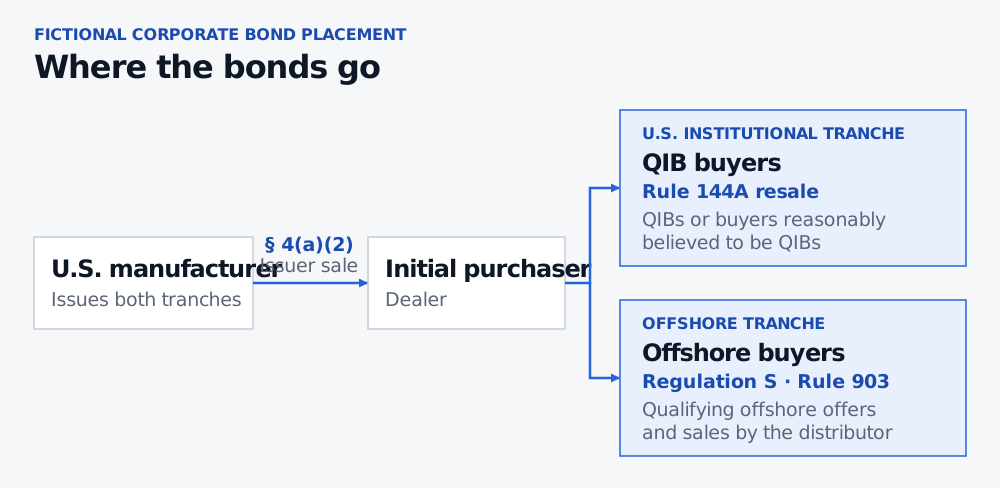
The issuer’s sale has its own exemption. The two branches show the initial purchaser’s separate distribution transactions.
Read the transfer terms for the line you hold
On a later secondary-market trade, the note’s legend and indenture can specify which transfer routes it permits and what the parties need to document. Rule 904 supplies a separate safe harbour for certain offshore resales. Rule 903 sets a 40-day distribution compliance period for Category 2 and Category 3 debt, while Category 1 has no such period under that rule. When the period ends, the period-specific conditions fall away. A later U.S. resale still has its own registration or exemption basis and may require transfer documentation. Rules 902(f)–(g) · Rule 903(b) · Rule 904
Forestar Group’s March 2025 indenture illustrates the difference. It describes separate 144A and Reg S global notes and requires a certification for transfers from the 144A line into the Reg S line. It also sets separate terms for removing the Reg S legend and for exchanging interests in a note carrying the Restricted Notes Legend. A single date on a security record would miss that distinction. Forestar indenture, Appendix A §§ 2.1 and 2.3
A registered exchange offer can change which line an investor holds. In its January 2026 prospectus, Crown Americas offered registered notes in exchange for validly tendered old notes under a registration rights agreement. The new notes represented the same debt. Old notes left outstanding retained their transfer restrictions. An analyst comparing the lines can distinguish those restrictions and the buyers they reach from the credit risk of the underlying debt. Crown Americas exchange prospectus
The SelfMadeQuant lesson on the convertible market, prospectus and participants applies the distinction to convertible allocations and explains why deal documents matter to a trading desk. The preview is public and the full lesson requires membership.
Sources
U.S. rules and filings checked 8 November 2026.
- Securities Act § 5, 15 U.S.C. § 77e
- Securities Act § 4(a)(2), 15 U.S.C. § 77d(a)(2)
- Rule 144A, 17 CFR § 230.144A
- Regulation S scope, Rule 901 and definitions, Rule 902
- Regulation S offshore distribution, Rule 903, offshore resales, Rule 904 and domestic issuer equity resale limitations, Rule 905
- SEC Division of Corporation Finance, Rule 144A interpretations, § 138
- Forestar Group, indenture dated 14 March 2025, Appendix A
- Crown Americas, exchange offer prospectus dated 30 January 2026