The debt service coverage ratio (DSCR) divides the cash or income available for debt service by the debt payments for the same period. It measures how much room a borrower has to absorb lower income or higher payments. Debt yield divides a property's annual net operating income by the loan amount. It lets a lender compare how much property income backs each dollar lent even when loans have different payment schedules.
How much cash is available for the next payment?
In project finance, the numerator is usually cash flow available for debt service (CFADS). It measures the project cash available to the debt being tested, after applicable operating costs and cash taxes and before paying lenders or distributing cash to equity. In a simple schedule, debt service is the sum of scheduled principal and cash interest. Use the same period and currency on both sides and enter the amounts due as positive numbers. World Bank PPP Resource Center, Debt Service Cover Ratio
A fictional project has USD 120,000 of CFADS for one six-month period, with USD 70,000 of principal and USD 30,000 of cash interest due. Assume these are the only required debt payments in the period and the cash arrives by the payment date.
The project has USD 1.20 of available cash per USD 1 of scheduled payments, leaving USD 20,000 after debt service. At 1.00× the defined cash exactly covers the payments for the period. An annual ratio can hide a shortfall at an earlier payment date if cash arrives later in the year. Lenders use period-by-period forecasts for debt sizing and may use a trailing or forward-looking window for a covenant.
What changes for a property loan?
For income-producing commercial real estate, the OCC handbook uses underwritten net operating income (NOI) divided by annual debt service. Its NOI convention deducts an allowance for replacing capital items even if the borrower has yet to set aside that cash. The loan documents can define income and expenses differently for covenant testing. OCC, Commercial Real Estate Lending, pp. 42–44 and glossary
Take a fictional property with USD 120,000 of annual underwritten NOI, a USD 1.5 million loan at origination and a USD 2 million appraised value. The loan is the only lien and the property is the only collateral. Consider two possible schedules with annual debt service of USD 100,000 and USD 125,000.
| Measure | Calculation | Schedule A | Schedule B |
|---|---|---|---|
| DSCR | Annual NOI ÷ annual debt service | 1.20× | 0.96× |
| Debt yield | Annual NOI ÷ original loan amount | 8% | 8% |
| Loan-to-value (LTV) | Original loan amount ÷ appraised value | 75% | 75% |
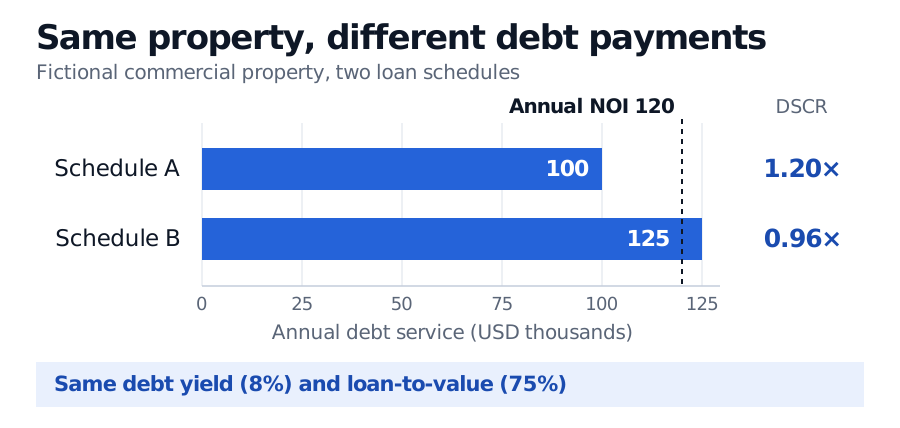
The dashed line marks the annual NOI available under this underwriting convention. Moving the payment past that line takes coverage below 1.00×.
Schedule B needs USD 5,000 more than the underwritten income provides. The debt yield stays at 8% because the income and amount lent are fixed. LTV stays at 75% because the collateral value also stays fixed. At the same NOI and DSCR, a lower debt yield means a larger loan carries the same annual payment. A lower rate or slower principal repayment can make that possible. OCC, Commercial Real Estate Lending, Debt-Service Coverage Ratio and Debt Yield
What does the agreement test?
For a covenant, check the definitions of cash flow and debt service, the test dates and what happens if the test fails. In Atlantic Aviation's 2007 loan agreement, for example, the debt service definition included specified fees and net scheduled hedge payments. The agreement required both backward- and forward-looking coverage tests for certain distributions and treated the required debt-service reserve balance as a separate distribution condition. A borrower can cover the scheduled payment and still be barred from distributing cash to equity. Atlantic Aviation loan agreement, §§ 6.1(e), 9.6(a)(ii) and Appendix A