A par FX forward applies one rate to a strip of delivery dates. See how discount factors and notionals set the rate and why individual dates can have nonzero value.
Par Forwards and Forward Strips
An FX forward strip is a set of FX forward contracts for different settlement dates. A par forward is a strip with one exchange rate for all dates, set so the strip as a whole starts with zero clean present value. A treasury team buying euros for a series of invoices can budget at one dollar cost per euro while still matching the amount and date of each invoice. HDFC Bank, Par Forward Contracts, §1.1
Price the difference on each date
Take the buyer's side. On date Ti the buyer receives Ni units of foreign currency and pays NiK units of domestic currency. Both the common delivery rate K and the fair single-date forward rate Fi are in domestic currency per foreign unit. Let Di be today's domestic discount factor to that exact settlement date.
Assume deliverable forwards with consistent domestic-currency collateral terms. Use same-time, matched-date fair forward rates and the domestic discount curve for those terms. Work at clean mid-market value with bid–ask spreads, fees and credit adjustments excluded. The fair forward for each date may already reflect the market's cross-currency basis. Moreni and Pallavicini, FX Modelling in Collateralized Markets, §2.2.1
To value the buyer's contract, add an offsetting sale of the same foreign amount for NiFi domestic on the same date. The offsetting forward starts at zero value. The foreign deliveries cancel, leaving a certain domestic cash flow of Ni(Fi−K). Its present value is DiNi(Fi−K), positive to the buyer when the contracted price is below the market forward for that date. The common rate sets the sum of these present values to zero.
i∑DiNi(Fi−K)=0⟹Kpar=∑iDiNi∑iDiNiFi.
Each date's weight is its foreign notional times its domestic discount factor. With equal notionals, only the discount factors matter. With unequal notionals, a larger amount gives that date's forward rate more weight, all else equal. For positive notionals and discount factors the par rate lies between the lowest and highest fair forward rates.
Two invoices, one budget rate
A fictional US importer must buy EUR 100,000 in one year and another EUR 100,000 in two years. Every exchange rate below is in USD per EUR. All inputs are stipulated at inception.
Settlement
Fair forward rate
USD discount factor
USD paid at each date's own rate
USD paid at the common rate
Year 1
1.10
0.95
110,000.00
114,864.86
Year 2
1.20
0.90
120,000.00
114,864.86
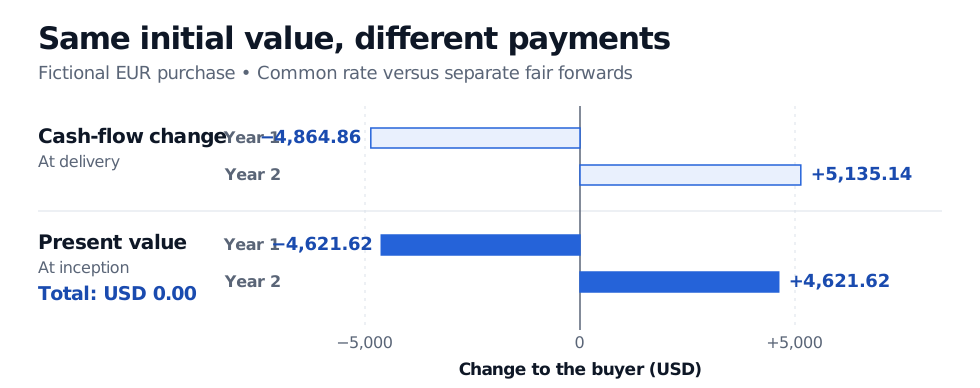
With equal euro notionals, the common rate is (0.95×1.10+0.90×1.20)/(0.95+0.90)≈1.148648649. The buyer pays more on the first date and less on the second. At inception the first contract is worth about −USD 4,621.62 to the buyer and the second about +USD 4,621.62. Their clean present values cancel at the unrounded rate. A simple average of 1.15 would give the buyer an initial value of −USD 250 because the earlier, cheaper forward has the larger discount weight.
In a fictional two-date euro purchase, the buyer pays USD 4,864.86 more in year 1 and USD 5,135.14 less in year 2 at the common rate. Discounted to today, those differences are minus and plus USD 4,621.62, summing to zero.
Relative to separate fair forwards, the common rate moves dollar outlay from year 2 to year 1. Only the discounted differences offset.
The locked rate stays in the contract as market forwards move. If an invoice is delayed or cancelled, the forward still comes due on its agreed date. Closing it early can cost money or produce a gain, depending on replacement rates and the trade's unwind terms. A cross-currency swap generally exchanges interest payments on currency principals and may exchange the principals themselves. The strip here fixes outright currency purchases on a schedule, with no interest coupons. HDFC Bank, §§2.1 and 4 · Moreni and Pallavicini, §3.2
To see how a single-date FX forward relates to spot and the two currencies' interest rates, read the Spot, forwards, and interest rates section of SelfMadeQuant's FX lesson. The full lesson is available with a free account. FX, Finance Primer