An
accelerated share repurchase (ASR) is a share buyback in which a company typically prepays a dealer and receives a large block of its own shares upfront. A forward contract sets the final economics using an agreed price formula over a later calculation period. The company can reduce outstanding shares on the initial delivery date while the final quantity is still unknown. That gap matters when forecasting
earnings per share (EPS).
SLM ASR master confirmation,
SLM Form 10-Q, Notes 10–11.
The dealer can borrow shares from stock lenders and deliver them to the issuer in the initial repurchase. The issuer takes those shares out of circulation. The dealer owes equivalent shares to its lenders and can buy shares in the market to close that borrow. The dealer’s covering trades and the issuer’s purchase from the dealer are separate transactions. The
Short Selling lesson (public preview, full lesson for members) explains the borrow-and-return leg.
SLM ASR master confirmation, sections 1 and 10(b) and Schedule A,
SEC staff FAQ on Rule 10b-18, question 13.
In a fixed-cash deal, the settlement formula often divides the prepayment by a price based on volume-weighted average prices (VWAPs). For example, SLM’s March 2026 confirmation averages eligible daily VWAPs over the calculation period, then adjusts the price under the contract. The terms determine the eligible trades, the end of the window, price adjustments and what happens if the initial delivery exceeds the calculated final quantity. SLM’s confirmation makes cash the default in that last case and gives the issuer a conditional share-settlement election.
SLM ASR master confirmation, Valuation, Settlement Terms and Annex A.
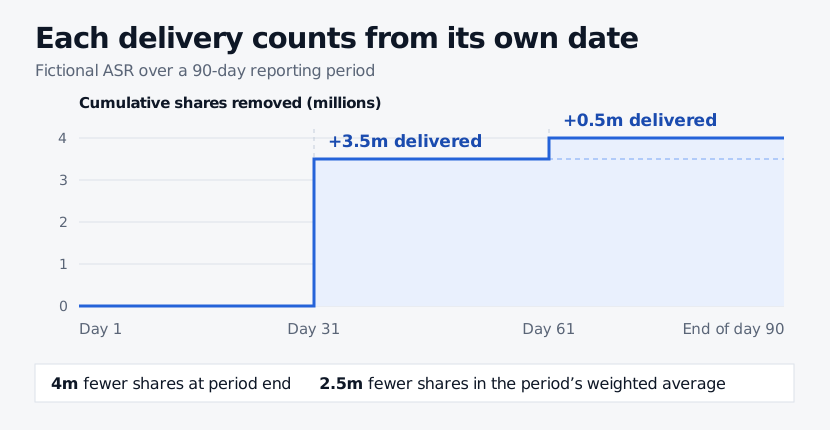
Suppose a fictional issuer prepays 100 million currency units (CU) and receives 3.5 million shares upfront. The contract formula yields a final effective price of 25 CU per share in this scenario. Assume no discounts, caps or other settlement adjustments. The prepayment buys 4 million shares in total, so the dealer delivers the remaining 0.5 million shares at settlement.
Suppose the company starts a 90-day reporting period with 100 million shares outstanding. The initial delivery comes at the start of day 31 and settlement at the start of day 61, with no other share changes. Outstanding shares run at 100 million, then 96.5 million, then 96 million for 30 days apiece. The quarter-end count is 96 million. The basic EPS denominator for the period is 97.5 million shares.
The difference can cross a reporting boundary. SLM reported receiving about 8.4 million shares on March 11, 2026. It completed the ASR on June 30 and received the final 0.9 million shares at settlement on July 1. Each delivery reduces the basic EPS share count from its acquisition date. The forward is assessed separately for diluted EPS while it is unsettled. The
treasury stock method used for option and warrant dilution assumes a hypothetical repurchase with exercise proceeds. The ASR deliveries are actual repurchases.
SLM Form 10-Q, Notes 10–11,
FASB ASU 2020-06, ASC 260-10-45-22 through 45-23 and 45-45 through 45-46.